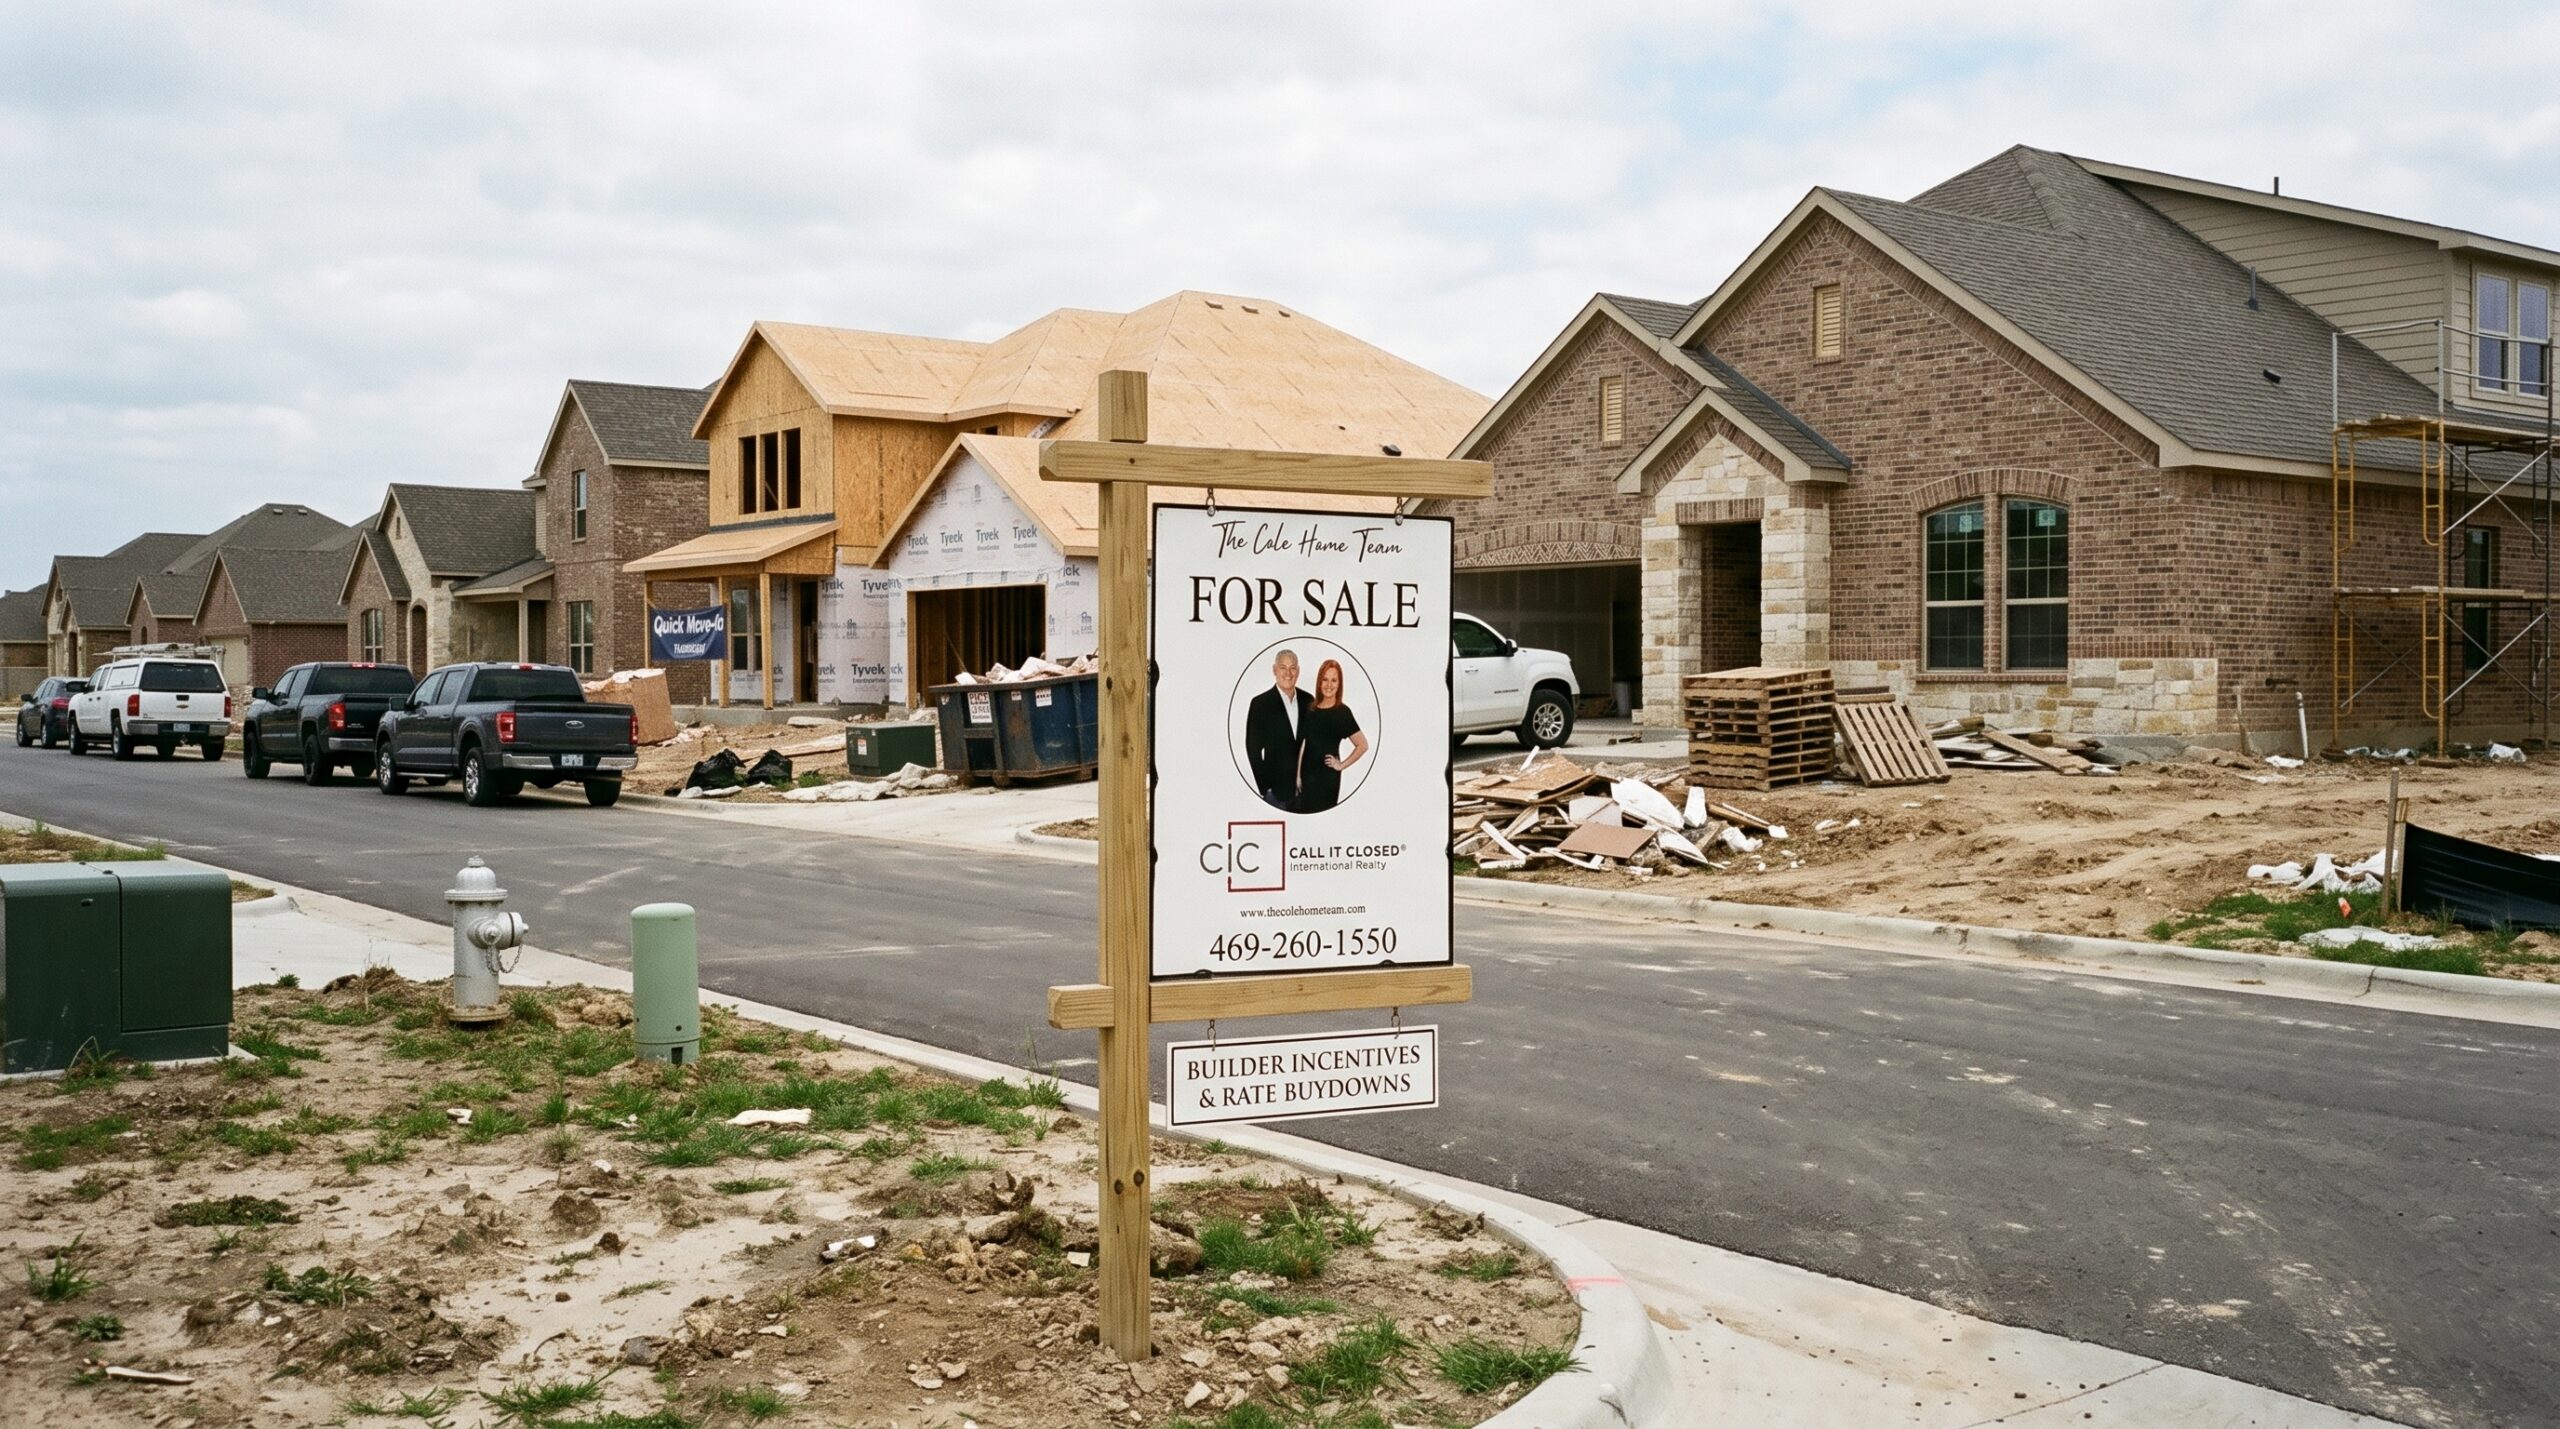
North Texas builders are carrying significantly more standing inventory than in previous years, shifting negotiating leverage decisively toward buyers. For anyone shopping for new builds in high-growth corridors like Forney, Celina, Princeton, Prosper, or Waxahachie, understanding how 2026 incentive packages operate is critical before stepping into a model home.
This guide breaks down how builder incentives work in practice, what the actual savings look like, hidden post-closing costs to prepare for, and how to maximize your leverage at the negotiating table.
Why North Texas Builder Discounts Are Substantial Right Now
Increased standing inventory is the primary driver of current buyer leverage. When builders carry completed spec homes on their balance sheets, daily carrying costs accumulate quickly. That financial pressure produces incentive packages that buyers in an inventory-constrained market would rarely see.
– Standard Incentive Value: Typical baseline incentive packages for North Texas new builds range from $8,000 to $25,000 in total value.
– Quick Move-In (QMI) Value: On completed inventory homes, stacked incentives can push total value well above $40,000 in combined credits, price adjustments, and rate buydowns.
Active production and semi-custom builders across the DFW metroplex—including Perry Homes, Highland Homes, D.R. Horton, Bloomfield Homes, Britton Homes, American Legend, Toll Brothers, and UnionMain Homes—each structure incentives differently. Comparing terms across builders in the same submarket yields substantial differences in long-term loan costs.
The 3 Main Types of Builder Discounts in 2026
1. Temporary Rate Buydowns (2-1 and 3-2-1)
A temporary buydown lowers your interest rate for the first one to three years of the loan before returning to the note rate.
– 2-1 Buydown: Year 1 interest rate is 2 percentage points below the full note rate; Year 2 is 1 point below; Year 3 onward returns to the fixed note rate.
– 3-2-1 Buydown: Year 1 interest rate is 3 percentage points below the note rate; Year 2 drops 2 points; Year 3 drops 1 point; Year 4 onward returns to the full rate.
Real-World Impact: On a loan with a 6.99% fixed note rate, a 3-2-1 buydown drops your Year 1 payment calculation to 3.99%, Year 2 to 4.99%, and Year 3 to 5.99%. The builder funds this subsidy upfront through their preferred lender. While temporary buydowns provide immediate cash-flow relief, buyers must budget for the step-up to the full note rate in Year 4.
2. Permanent Rate Buydowns
A permanent buydown uses discount points (typically 1 to 3 points paid upfront by the builder) to permanently lower the fixed interest rate across the entire 30-year term.
– The Catch: Permanent buydowns deliver maximum value if you hold the loan long-term. If you plan to sell or refinance within 3 to 5 years, a temporary buydown or direct closing credit may yield higher net savings.
3. Flex Cash, Design Credits, and Lot Premium Waivers
These incentives bypass interest rates and apply directly to purchase costs:
– Flex Cash Credits: DFW builders currently offer flex credits ranging from $15,000 to $40,000+, which buyers can apply toward closing costs, title fees, or interest rate adjustments.
– Design Center Credits: Upfront credits applied to flooring, countertop, or structural upgrades without requiring out-of-pocket cash at the design studio.
– Lot Premium Waivers: Complete or partial waivers on additional charges for corner lots, cul-de-sacs, or greenbelt-facing sites.
Note: DFW builders generally avoid direct list-price reductions whenever possible to protect appraisal comparables across the neighborhood. Instead, they expand the total incentive package while keeping base prices stable.
Quick Move-In (QMI) vs. Build-to-Suit Leverage
Quick Move-In / Spec Homes:
– Construction Status: Completed or near completion
– Incentive Leverage: Maximum (High builder holding costs)
– Customization: Pre-selected finishes
– Closing Timeline: 15 to 45 days
Build-to-Suit Contracts:
– Construction Status: Built from ground up after contract signing
– Incentive Leverage: Moderate (Lower immediacy for builder)
– Customization: Full design center flexibility
– Closing Timeline: 6 to 10 months
If your timeline permits a fast closing, prioritizing completed spec inventory yields the highest potential for stacked builder discounts.
The Tax Layer: MUD, PID, and Property Tax Realities
Builder incentives address the purchase price, but long-term affordability depends heavily on local tax structures in North Texas master-planned communities.
Understanding MUD and PID District Assessments
Municipal Utility Districts (MUDs) and Public Improvement Districts (PIDs) are local financing vehicles used to fund infrastructure like water lines, roads, and amenities. These assessments appear as additional line items on property tax bills.
– Monthly Impact: In high-growth submarkets including Celina, Prosper, Melissa, Lavon, Forney, and Argyle—combined MUD and PID assessments frequently add $300 to $500+ per month to standard escrow calculations.
– The Bare-Land Tax Trap: During Year 1, property taxes may be assessed only on the unimproved land value. In Year 2, when county appraisers assess the fully constructed home, escrow payments rise significantly. Buyers should always calculate debt ratios using full projected home assessments rather than initial closing statements.
Texas Homestead Exemptions & HOA Fees
– Homestead Exemption: The $140,000 Texas homestead exemption applies to school district taxes on primary residences but does not reduce separate MUD or PID obligations.
– HOA Dues: DFW master-planned communities typically charge $600 to $1,200+ annually in HOA fees, depending on amenity density (e.g., pools, fitness centers, trail networks).
Critical Buyer Protections Before Signing
1. Representation Requirement
Builder sales representatives represent the builder’s legal and financial interests. To retain independent buyer representation, your real estate agent must accompany you on your first physical or virtual visit to the model home. Unrepresented buyers who register independently often forfeit the ability to have dedicated representation paid for by the builder commission pool.
2. Side-by-Side Lender Comparison
Builder incentives are almost always conditional on using the builder’s affiliated or preferred lender. To verify the true value of the offer:
1. Request an official Loan Estimate from the preferred lender.
2. Request an unbundled Loan Estimate from an independent mortgage broker on the exact same day using identical loan terms.
3. Compare total loan costs over 3-, 5-, and 10-year horizons to determine whether the preferred lender’s incentives offset any rate or fee differentials.
Beyond advertised incentives, buyers can often negotiate:
– Full or partial lot premium waivers on standing inventory
– Appliance package inclusions (refrigerator, washer/dryer)
– Perimeter fencing inclusions
– Extended interest rate locks during construction delays
– Extended builder structural or system warranty coverage
Buyer Action Plan Checklist
[ ] Verify whether the property resides in a MUD, PID, or both, and obtain the total combined tax rate in writing.
[ ] Request the current internal builder incentive sheet, including unlisted standing inventory specials.
[ ] Run a same-day Loan Estimate comparison between the preferred lender and an independent lender.
[ ] Calculate total monthly payments using fully assessed home values, MUD/PID fees, HOA dues, and insurance.
[ ] Confirm independent buyer agent representation prior to visiting model homes.
Work With The Cole Home Team
Navigating North Texas new construction requires analyzing the complete financial picture from builder incentive structures and buydown math to MUD/PID tax assessments.
Robert and Mandy Cole specialize in representing buyers across Kaufman County, Rockwall County, and the broader DFW market including Forney, Terrell, Rockwall, Celina, Prosper, and Cedar Creek Lake. Builder promotions change frequently and unlisted spec inventory is rarely published online.
Contact The Cole Home Team today to receive an updated, unlisted inventory list and a custom builder incentive analysis for your target communities. Buyers pay zero out-of-pocket costs for dedicated representation.
Sources Referenced
- Builder Incentives for New Builds in Texas (2026) | LRG – Levi Rodgers Real Estate Group (lrgrealty.com)
- 2026 Guide to Buying New Construction in North Texas – Miranda Realty Team (mirandarealty.team)
- DFW Builder Incentives 2026: What You Need to Know – Zak Schmidt (www.zakschmidt.com)
Frequently Asked Questions
What are the typical incentives offered by North Texas builders in 2026?
North Texas builders are offering substantial incentives due to increased standing inventory. Standard packages range from $8,000 to $25,000, while quick move-in homes can see total value exceeding $40,000 through combined credits, price adjustments, and rate buydowns.
How do temporary rate buydowns work for new construction in North Texas?
Temporary rate buydowns, like 2-1 or 3-2-1 plans, lower your interest rate for the first one to three years of the loan. For example, a 3-2-1 buydown on a 6.99% note rate would result in a 3.99% rate in year one, 4.99% in year two, and 5.99% in year three, before returning to the full rate.
Should I choose a temporary or permanent rate buydown?
A temporary buydown offers immediate cash-flow relief, making it ideal if you plan to sell or refinance within a few years. A permanent buydown, funded by discount points, lowers your rate for the entire loan term and provides maximum value if you intend to hold the mortgage long-term.
What are the potential hidden costs associated with new builds in North Texas?
Beyond the purchase price, be aware of MUD and PID assessments which can add $300 to $500+ monthly to your escrow payments for infrastructure. Additionally, property taxes can significantly increase in the second year when appraisers assess the fully constructed home value.
How can I ensure I have independent representation when buying a new build?
To retain independent buyer representation, your real estate agent must accompany you on your first visit to the model home. Builders' sales representatives legally represent the builder's interests, and unrepresented buyers may forfeit the ability to have their own agent paid from the builder's commission.