Table of Contents
- Quick Answer: Is Now a Good Time to Buy in North Texas?
- What Are Mortgage Rates Expected to Do in 2027?
- New Construction in North Texas: Where Buyers Should Pay Attention
- Forney, Rockwall, and Terrell: Why Location Changes the Numbers
- Buy Now or Wait? A Practical Mortgage Payment Comparison
- When Buying Now Might Make Sense
- When Waiting Until 2027 May Be Smarter
- New Construction vs. Resale: Which Is the Better Deal?
- Five Questions to Ask Before Buying a Home in North Texas
- Before You Buy, Let's Compare Your Actual Options
Buying a Home in North Texas: Buy Now or Wait Until 2027?
By Robert & Mandy Cole | The Cole Home Team | October 2026
If you’re thinking about buying a home in Forney, Rockwall, Terrell, Heath, or the surrounding North Texas area, you’ve probably asked yourself one question:
Should I buy a house now, or wait until 2027 for better mortgage rates?
It’s a reasonable question. But here’s something many buyers overlook: the mortgage rate is only one part of the deal.
Between new construction incentives, available inventory, property taxes, and the possibility of negotiating with sellers, the home that makes financial sense today might not be the one you expect.
And waiting for lower interest rates doesn’t automatically mean you’ll save money.
Let’s look at what actually matters before making that decision.
Quick Answer: Is Now a Good Time to Buy in North Texas?
Buying now may make sense if you have stable income, manageable debt, sufficient savings, and find a home that fits your budget without depending on a future refinance.
Waiting until 2027 may be the better choice if you need to improve your credit, save more money, strengthen your financial reserves, or aren’t certain where you want to live.
For buyers considering new construction in Forney, Terrell, or nearby communities, builder incentives may also change the calculation.
The right decision isn’t simply about whether mortgage rates fall. It’s about what the home will actually cost you and whether that payment fits your financial goals.
What Are Mortgage Rates Expected to Do in 2027?
According to the Texas Real Estate Research Center at Texas A&M University, its September 2026 forecast projects 30-year fixed mortgage rates between 6% and 7% by August 2027.
Source: Texas Real Estate Forecast Through Summer 2027
That doesn’t mean rates can’t move outside that range. Forecasts change as inflation, economic conditions, and financial markets evolve.
But here’s the important point for buyers:
Waiting until 2027 doesn’t guarantee substantially lower mortgage rates, lower home prices, or a better overall deal.
If you’re financially prepared to buy, it may be worth comparing your options today rather than basing your entire decision on a prediction.
New Construction in North Texas: Where Buyers Should Pay Attention
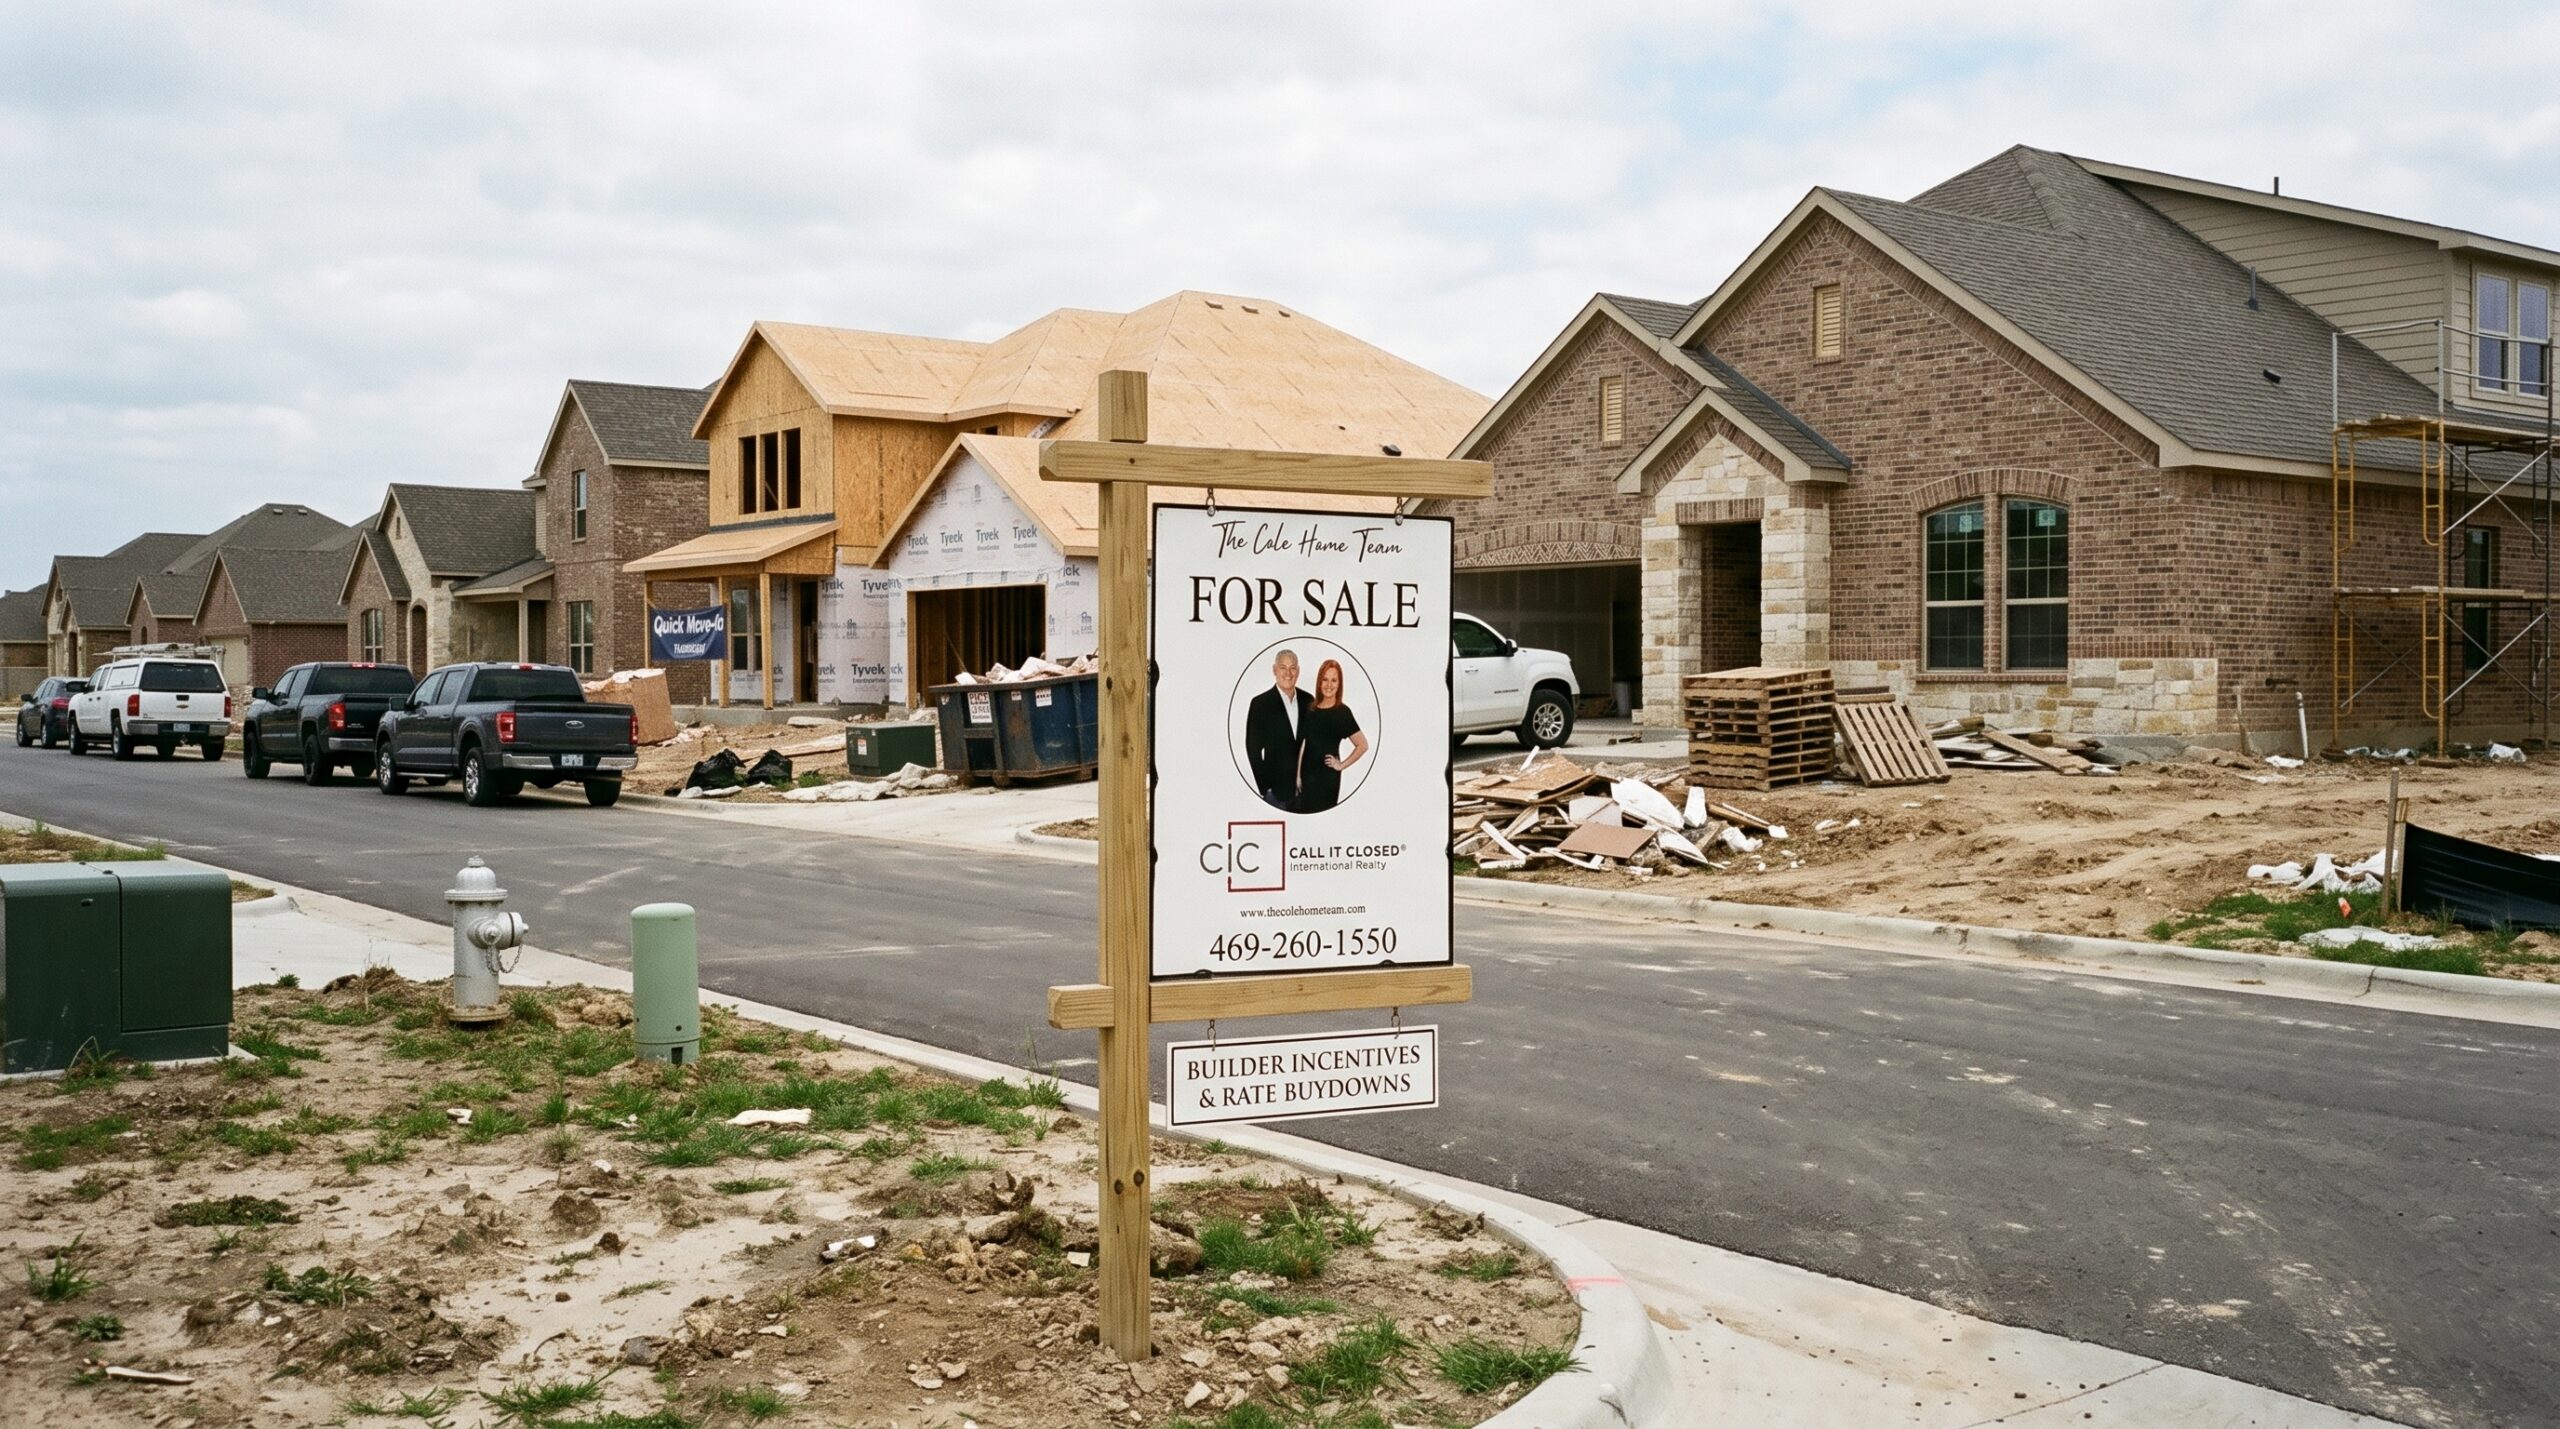
One of the biggest opportunities worth investigating in the Forney and Kaufman County area is new construction.
Builders may offer incentives to attract buyers, particularly on completed homes they want to sell.
Depending on the builder, community, financing terms, and availability, incentives can include:
Mortgage rate buydowns
Assistance with closing costs
Design center or upgrade allowances
Reduced prices on selected inventory homes
Special financing promotions through preferred lenders
Not every builder offers these incentives, and terms can change.
Why the Advertised Mortgage Rate Doesn’t Tell the Whole Story
Imagine two homes with similar prices.
One is a resale property with a standard mortgage.
The other is new construction with an advertised promotional rate.
At first glance, the new construction home may appear to be the better financial decision.
But what happens when you compare property taxes, insurance, HOA dues, MUD or PID obligations, lender fees, and the duration of the promotional rate?
That attractive monthly payment could look different.
The smartest buyers compare the total cost of ownership, not just the advertised interest rate.
Before You Visit a Builder’s Model Home
Here’s something worth understanding before you walk through the door.
The builder’s sales representative works for the builder. Their role is to sell the builder’s homes.
A buyer’s real estate agent can help evaluate different communities, compare incentives, review contract considerations, coordinate inspections, and negotiate where opportunities exist.
Builder policies concerning agent registration and compensation vary. Some require an agent to be identified during the initial visit or registration.
That’s why it’s worth discussing representation before touring model homes or signing paperwork.
Want help comparing builders before you visit? Contact The Cole Home Team at 469-474-9129.
Forney, Rockwall, and Terrell: Why Location Changes the Numbers
Buying in North Texas isn’t a one-size-fits-all decision.
Two homes with the same purchase price can have different ongoing expenses depending on where they’re located.
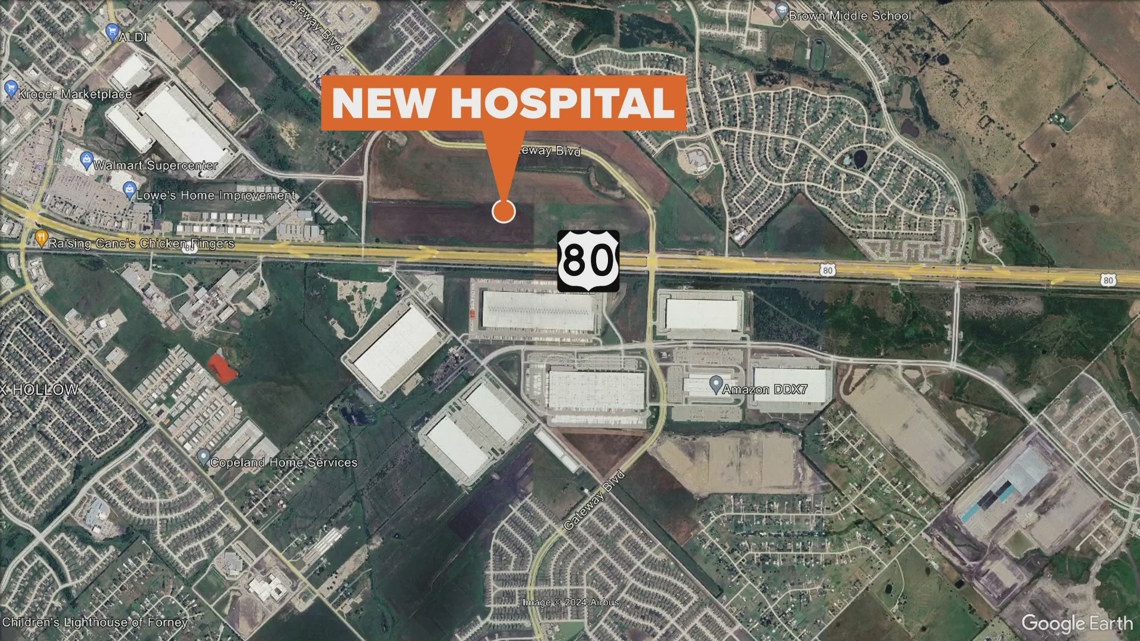
Forney and Kaufman County
Forney-area buyers should carefully evaluate new construction communities, commuting needs, school district boundaries, property taxes, and any special district assessments.
In particular, buyers should understand whether a property falls within a Municipal Utility District (MUD) or Public Improvement District (PID).
These obligations can affect the true cost of homeownership.
For a closer look, read our guide: What Forney’s Sticker Prices Hide: The MUD and PID Layer.
Rockwall and Heath
Buyers considering Rockwall and Heath may be comparing established neighborhoods, newer communities, lot sizes, commute preferences, and lifestyle priorities.
The right choice depends on the individual property and its total cost, not simply the city name or asking price.
Terrell and Surrounding Communities
Terrell-area buyers should compare available resale properties and new construction opportunities, including the costs associated with commuting, property taxes, maintenance, and neighborhood amenities.
A lower purchase price doesn’t always translate into the lowest overall monthly expense.
Buy Now or Wait? A Practical Mortgage Payment Comparison
Let’s use a hypothetical example.
Assume you’re purchasing a $350,000 home with 5% down.
That produces a starting loan amount of $332,500 before any financed mortgage insurance or other fees.
30-Year Fixed RateApproximate Monthly Principal & Interest6.75%$2,1576.25%$2,0475.75%$1,941
Illustrative estimates only, rounded to the nearest dollar. These figures exclude property taxes, homeowners insurance, mortgage insurance, HOA dues, MUD/PID obligations, closing costs, and other expenses. Actual loan pricing and eligibility vary.
A lower rate certainly matters. But it is not the only variable.
If a buyer waits and the home price changes, the amount borrowed may also change. If the buyer purchases now with a builder incentive, that changes the calculation again.
A temporary rate buydown also differs from a permanent fixed-rate reduction. Buyers need to know what their payment will be after any temporary promotional period expires.
Never purchase a home you cannot comfortably afford today based solely on the hope of refinancing later.
When Buying Now Might Make Sense
Buying before 2027 could be worth considering when:
You have reliable income and sufficient emergency savings.
Your expected housing payment fits comfortably within your budget.
You plan to remain in the home long enough to justify transaction costs.
You find a home that meets your needs at a price you can support.
Available builder incentives or resale negotiations improve the overall deal.
You don’t need to predict the perfect market bottom to make a financially responsible purchase.
You need to understand the numbers and make sure they work for you.
When Waiting Until 2027 May Be Smarter
There are also perfectly good reasons not to buy immediately.
Waiting may make sense when:
Your credit profile needs improvement.
You’re still saving for a down payment and closing costs.
Your employment or income situation is uncertain.
Your monthly budget would be stretched too thin.
You don’t know whether you’ll remain in the area.
You haven’t found a home that meets your needs.
Homeownership comes with maintenance, repairs, insurance, taxes, and unexpected expenses.
Buying simply because a builder is advertising an incentive is not a good strategy if the underlying purchase doesn’t fit your financial situation.
New Construction vs. Resale: Which Is the Better Deal?
This is one of the most important comparisons buyers can make in North Texas.
New ConstructionResale HomesMay offer builder financing incentivesMay offer seller concessionsTypically newer major systemsEstablished property condition variesMay include builder warrantiesInspection and maintenance history matterPossible MUD/PID obligationsSpecial district obligations vary by propertyUpgrades and lot premiums may add costRepairs and updates may add costBuilder contract terms and deadlinesNegotiated contract terms and deadlines
Neither option is automatically better.
The best value is the property that meets your needs with the most favorable combination of price, financing, condition, location, and ongoing expenses.
Five Questions to Ask Before Buying a Home in North Texas
Before committing to a property, ask:
1. What is my realistic monthly payment?
Include principal, interest, taxes, insurance, mortgage insurance, and applicable HOA or special district expenses.
2. Are there builder incentives I should compare?
Ask about lender requirements, expiration dates, temporary versus permanent buydowns, and total closing costs.
3. What does the property tax situation look like?
Review the property’s applicable taxing jurisdictions and assessments. For new construction, remember that current tax estimates may not reflect the completed home’s eventual taxable value.
4. Am I comparing enough properties?
Review both new construction and resale opportunities before assuming one is the better value.
5. Who is representing my interests?
Understand your representation options, agency agreements, and compensation terms before signing.
Frequently Asked Questions
Should I buy a house now or wait until 2027 in North Texas?
Buying now may make sense if you’re financially ready and can secure a property with a sustainable payment. Waiting may be better if you need more savings, improved credit, or greater financial stability. Future rates and prices are uncertain.
Will mortgage rates drop in 2027?
Some forecasts anticipate moderate changes, but no forecast guarantees a specific mortgage rate. The Texas Real Estate Research Center projected a 6%–7% range for August 2027 in its September 2026 outlook.
Are builders offering incentives in Forney, TX?
Some builders may offer rate buydowns, closing-cost assistance, upgrades, or other promotions. Offers vary by builder, home, financing arrangement, and date. Buyers should verify current terms before relying on an advertised incentive.
Do I need a Realtor when buying new construction?
You can purchase directly from a builder, but the builder’s sales team represents the builder’s interests. Having your own agent can provide independent assistance with property comparisons, contract considerations, inspections, and negotiations. Discuss representation and any fees before signing an agreement.
What should I compare besides mortgage rates?
Compare total monthly payment, property taxes, insurance, HOA dues, MUD/PID obligations, lender fees, maintenance, and the property’s condition. For promotional financing, verify whether the rate is temporary or permanent.
Before You Buy, Let’s Compare Your Actual Options
Here’s what we believe at The Cole Home Team:
You shouldn’t have to guess whether now is the right time to buy a home.
And you shouldn’t have to visit five different builders just to figure out which incentives are actually worth considering.
Whether you’re a first-time buyer, relocating to North Texas, or looking for your next home, we can help you evaluate your options.
Request Your Personalized North Texas Homebuyer Comparison
We’ll help you review:
New construction and resale homes that match your needs
Builder incentives available on properties you’re considering
Financing questions to discuss with your lender
Property tax and special district considerations
The advantages and trade-offs of buying now versus waiting
No pressure. No obligation. Just a practical conversation about your options.
The Cole Home Team — Robert & Mandy Cole
Call or text: 469-474-9129
Email: robert@thecolehometeam.com
Website: https://thecolehometeam.callitclosed.com
Mortgage forecasts, builder promotions, property availability, and financing terms are subject to change. Consult a licensed lender for individualized loan terms and payment estimates.